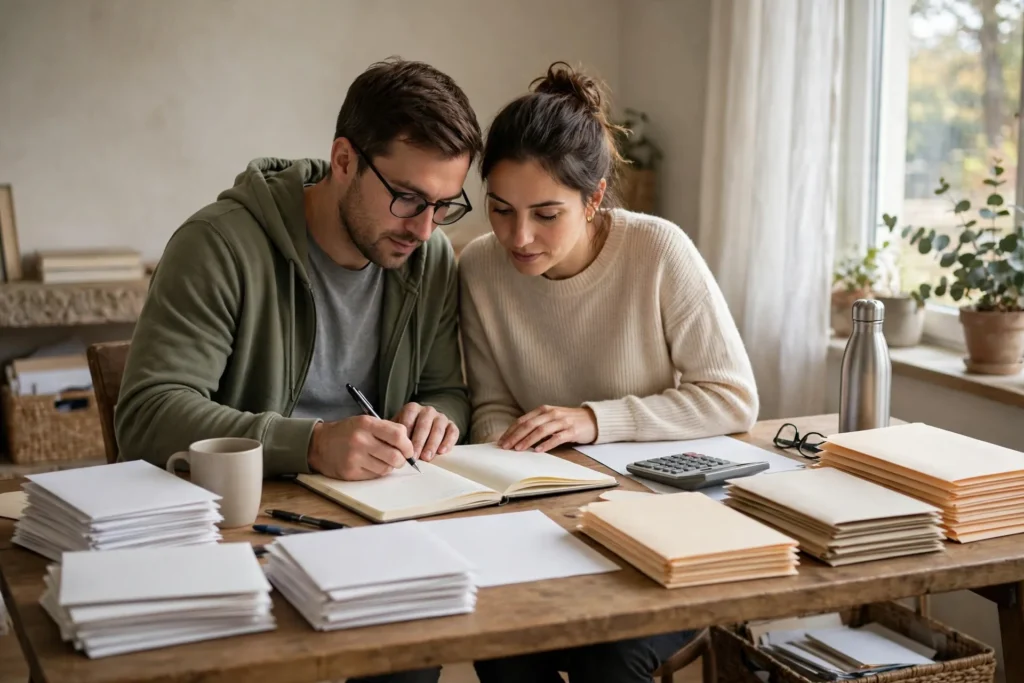
Tax season is one of the most practical times of year to build or refresh your house hunting wish lists. While you gather pay stubs, W-2 forms, and last year’s bank statements, you are handling exactly the paperwork that shapes what you can look for — and a wish list written with those documents on the table is far more honest than one written from memory. You do not need to finish your return before you start; you just need to use the season’s focus while you have it.
Key Takeaways
- Tax season puts your real income paperwork in one pile — much of it the same documentation a lender will later ask for during pre-approval.
- A wish list updated during tax season reflects your actual household income and spending, not hopeful guesses made months ago.
- If a refund is coming, decide together where it goes before it arrives, and do not let it quietly inflate your wish list.
- Use the season to re-sort must-haves from nice-to-haves while your budget picture is fresh and specific.
- Tax rules, deadlines, and forms change, so check the current details on IRS.gov instead of relying on last year’s memory.
- Save the updated wish list somewhere you will both see it, ready for the rest of your home search.
In This Guide
- Why Tax Season Is Wish List Season
- Step 1: Let Your Tax Paperwork Tell the Truth About Your Budget
- Step 2: Decide What a Refund Means Before It Arrives
- Step 3: Re-Sort Your Must-Haves and Nice-to-Haves
- Step 4: Check the List Against the Year Ahead
- A Quick Map: Tax Paperwork and Wish List Decisions
- A Worked Example: One Couple, One Tax Season
- Frequently Asked Questions
- Your Next Step
- Related Articles
Why Tax Season Is Wish List Season
Most couples write their first house hunting wish list at an excited moment — often right after deciding to buy, sometimes right after scrolling through listings late at night. The problem is that excitement is a poor accountant. In that mood, it is easy to write down a price range you have never tested against your real budget, or to list features you have seen in photos rather than things your daily life actually requires.
Tax season corrects for that. For a few weeks each year, your household’s money life is spread out in front of you in black and white: what each of you earned, what was withheld, what you paid in student loan interest or childcare costs, what your side income looked like. That is a rare, honest snapshot, and it pairs naturally with the bigger homebuying picture in our first-time homebuyer roadmap for couples, which treats your budget as the foundation every later step stands on.
There is a practical bonus, too. Organizing documents for your return means you are already halfway to organizing the folder you will need when you talk to a lender. The wish list you write this month can become the cover page of that folder: what you are looking for, in what range, and why.
Step 1: Let Your Tax Paperwork Tell the Truth About Your Budget
Start with income, because income is where wish lists most often drift away from reality. As you work through your return, note each income source your household actually had last year: wages for each partner, self-employment or freelance income, tips, rental income if you have any, and anything else that shows up on the forms. Write the household total on a sticky note and put it on top of your wish list draft. That number is your anchor.
Then look at the quieter lines. Your return and the statements you gathered alongside it show what you actually spent on the unglamorous parts of life — interest, insurance premiums, childcare, commuting. None of these numbers belongs on a wish list, but together they remind you what your monthly life costs before a mortgage enters it. A wish list that assumes every dollar of income is available for housing will not survive first contact with a real monthly budget.
A few honest cautions belong here:
- Last year is a snapshot, not a promise. If one of you changed jobs, worked unusual overtime, or had a one-time windfall, say so on the page. A wish list built on a year you cannot repeat is a wish list that will disappoint you.
- Self-employment and gig income deserve extra care. This income can swing from year to year, and lenders tend to look at it differently from wages. Note the pattern across years if you have it, and keep the paperwork for each year together.
- Do not adjust the numbers to fit the list. If the gap between your income and your dream home is real, the kind response is to adjust the list — a different neighborhood, a smaller home, a longer saving timeline — not to round your income up in your head.
This step is not about doing a lender’s job. It is about making sure the wish list the two of you argue over is at least arguing about real numbers.
Step 2: Decide What a Refund Means Before It Arrives
Many households receive a tax refund, and many others owe a balance instead. Either outcome carries information for your house hunt, and both deserve a calm, planned response rather than a surprised one.
If you are expecting a refund, talk about it before it lands in your account. Money that arrives without a plan tends to evaporate into small treats and forgotten purchases. Money with a job assigned — added to the down payment fund, held as a cushion for moving costs, or used to pay down a balance that is worrying you — quietly moves your home search forward. The size of the refund does not change this logic; a modest refund with a plan does more for your house hunt than a large one without one.
Just as important is what a refund should not do. A refund is last year’s money coming back to you; it is not a raise, and it does not recur every month. So it should not be the reason your wish list gains a more expensive neighborhood or an extra bedroom. Use one-time money for one-time purposes, and let your recurring income — the kind you documented in Step 1 — set the recurring shape of your list.
If you owe taxes instead, treat that as useful information too. It may mean your monthly cash flow has less slack than you assumed, or simply that your withholding needs attention. Either way, knowing it in February is far better than discovering it after you have fallen in love with a home. Adjust the list now, while adjusting is free.
Step 3: Re-Sort Your Must-Haves and Nice-to-Haves
With your budget picture fresh, sit down with your existing list — or start one using the weekend method in our guide to setting up house hunting wish lists — and sort every item into three honest piles.
- Must-haves are the things your daily life genuinely requires: a commute you can sustain, enough bedrooms for the household you have or are planning, a layout that works for a disability or a work-from-home job, a school or care arrangement you are not willing to uproot.
- Nice-to-haves are things you would enjoy but could live without or add later: a finished basement, a particular style of kitchen, a big yard, a garage with extra storage.
- Deal-breakers are the short list of things that end a conversation about a home immediately, whatever its other charms.
Tax season helps this sorting in a specific way: your paperwork reminds you which parts of your life are fixed and which are flexible. If your return shows significant commuting costs, a shorter commute may deserve promotion from nice-to-have to must-have. If it shows you spent heavily on a storage unit last year, space may matter more than you admitted. Let the documents argue with the daydreams, and write down what you decide so future-you does not have to reconstruct the reasoning.
Expect some disagreement here, and welcome it. The point of doing this in a calm season, months before an offer, is that you can afford to hear “the third bedroom matters more to me than the yard” as information rather than as a crisis. Each of you should be able to point to at least one item on the must-have list and say: this one is mine, and here is why.
Step 4: Check the List Against the Year Ahead
A tax return describes the year behind you. Your wish list describes the home ahead of you. The last step of a tax-season refresh is to look forward and ask what is likely to be different by the time you are actually touring homes and making decisions.
Walk through the usual suspects together. Is either of you expecting a job change, a new schedule, or a return to school? Is a baby, an adoption, or a family member moving in part of the realistic picture? Are you hoping to buy within a few months, or is this a longer runway where the list itself will be revised again? Our companion guide on how often couples should review their house hunting wish lists goes deeper on timing, but the tax-season version of the question is simple: does this list describe the household we are becoming, or only the household we were?
Finally, give the finished list a date and a home. Write the date at the top, save a photo or copy where both of you can find it, and note one or two triggers that should prompt the next review — a job offer, a new savings milestone, a change in family plans. A dated list with named triggers stays a working document instead of becoming a forgotten artifact.
A Quick Map: Tax Paperwork and Wish List Decisions
| Paperwork in front of you | What it can tell your wish list |
|---|---|
| W-2 forms and pay stubs | Your steady household income — the anchor for a realistic price range |
| Self-employment and gig records | How variable your income is, and how much caution the list needs |
| Refund or balance due | Whether one-time money can help the down payment fund — or cash flow needs attention first |
| Interest and expense statements | What your current life already costs each month before housing changes |
| Childcare and family-related forms | Whether space, schools, and commute deserve must-have status |
A Worked Example: One Couple, One Tax Season
Meet Maya and Jordan, a fictional couple invented for this example. Every number in their story is made up, uses round figures, and is labeled invented on purpose — real households and real refunds vary enormously.
Maya and Jordan had a wish list from the previous summer: four bedrooms, a big yard, a particular neighborhood, and a price range they had picked because it “felt about right.” During tax season, they spread out their paperwork. Their W-2 forms showed a combined income lower than the number they had been casually quoting each other, because Jordan had switched to a four-day schedule mid-year — a change they loved and had somehow never applied to the house math. Their invented refund in this example is $2,400, and before it arrived they agreed together that it would go straight into their down payment savings rather than toward a weekend trip.
With those two facts on the table, the list changed without any drama. The fourth bedroom moved from must-have to nice-to-have. The neighborhood stayed, but they added two adjacent areas they had been ignoring. The price range came down to one their actual income supported, and — this is the part couples often miss — they both felt better, because the list finally described a search that could succeed. They dated the new list, saved it to a shared folder, and wrote “review again if Maya’s contract renews in the fall” at the bottom.
Frequently Asked Questions
Do we need to file our taxes before updating our wish list?
No. The value of tax season is the paperwork-gathering itself, and that happens before you file. Once your W-2 forms, pay stubs, and statements are in one place, you have everything you need for a wish list refresh. Filing can happen on its own schedule.
Should a tax refund change the price range on our wish list?
Generally, no. A refund is one-time money, while a mortgage payment is a recurring one. A refund can sensibly boost your down payment savings or your moving-cost cushion, but letting it raise your ongoing price range is how households end up stretched every month for the sake of one good month.
What if we owe taxes this year?
Treat it as information, not failure. Owing a balance may signal that your withholding needs adjusting or that your monthly cash flow has less room than you assumed. That is exactly the kind of fact a wish list should absorb early, while changing the list costs nothing.
Our income changed a lot last year. Which year should the list reflect?
Reflect the year you can reasonably expect to repeat. If last year included a one-time bonus, unusual overtime, or a job you have since left, say so on the page and plan from the steadier number. A wish list built on your best-ever year is a recipe for disappointment.
Where can we check current tax deadlines and rules?
Use IRS.gov, the official source, for current filing deadlines, form changes, and withholding tools. Tax details change from year to year, so confirm anything you are relying on there rather than trusting last year’s memory or a social media post. For a complicated situation, a licensed tax professional can advise on your specific circumstances.
How is this different from just reviewing our wish list any time?
The review itself is the same; the season simply makes it easier and more honest. Tax season concentrates your real income documents, prompts a household money conversation you were going to have anyway, and lands early enough in the year to shape the spring and summer search. It is an anchor date with paperwork attached.
Your Next Step
This week, while your tax documents are out, set aside thirty minutes together: write your actual household income at the top of your wish list, sort every item into must-have, nice-to-have, or deal-breaker, and date the page. That single half hour turns tax season into the starting gun for a calmer, more realistic home search.
Related Articles
- Buying Your First Home Together: A Roadmap From Saving to Keys
- How to Set Up House Hunting Wish Lists in One Focused Weekend
- How Often Should Couples Review Their House Hunting Wish Lists?
This article is for general educational purposes only and is not financial, tax, legal, or investment advice. Consult a licensed professional about your situation.