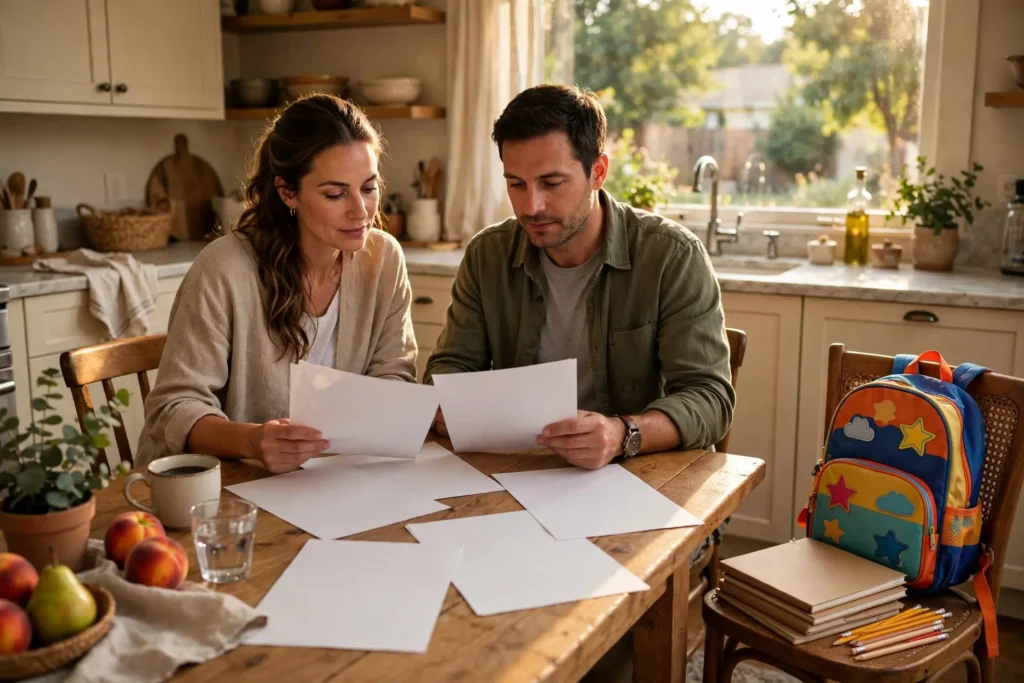
Back-to-school season is one of the most useful times of year for a couple with a self-employed partner to review their insurance — not because the policies change in the fall, but because the family’s schedule, childcare, and cash flow all change at once. The self-employed partner is usually the one who absorbs the new school-year logistics, which makes both their time and their income protection worth a fresh look. An hour with the paperwork in late summer can surface renewal dates, enrollment windows, and coverage gaps while there is still time to act on them.
Key Takeaways
- Back-to-school season works as an insurance checkpoint because routines, childcare costs, and the self-employed partner’s working hours all shift at the same time.
- The partner without a job-based safety net is often the one who absorbs school pickups, sick days, and schedule surprises — and that flexibility is itself an income risk.
- The review is simple: health coverage, income protection, life insurance and beneficiaries, then the paperwork itself.
- Fall is also when many employers hold their annual enrollment period, so a late-summer review means decisions are made before deadlines arrive.
- Write down renewal dates, premium due dates, and what you decided, so next year’s review starts from a list instead of from memory.
In This Guide
- Why Back-to-School Season Is a Natural Checkpoint
- The Schedule Change Is an Insurance Issue
- What to Review, One Policy at a Time
- The Paperwork Hour: What to Pull Out
- Renewals and Enrollment Windows Ahead
- A Worked Example: One Couple’s Late-Summer Hour
- Frequently Asked Questions
- Your Next Step
- Related Articles
Why Back-to-School Season Is a Natural Checkpoint
Every family with school-age children knows the feeling: the last weeks of summer end, and almost overnight the household runs on a new clock. School start times set the mornings. Afternoons fill with pickups, practices, and homework. Money moves too — supplies, fees, new shoes, after-school care. For a couple where one partner is self-employed, there is a quieter change underneath the visible ones: the self-employed partner’s work bends around the school day, because their schedule is the flexible one.
That is what makes the season such a good anchor for an insurance review. Good reviews happen when something prompts them, and most couples do not lack good intentions — they lack a trigger. Back-to-school season is a trigger that arrives on its own, every year, at roughly the moment when fall enrollment windows and policy renewals start appearing. Tying the review to the school calendar means it survives busy years, because the school year always shows up.
There is a practical bonus, too. The same weeks that fill your kitchen table with school forms, supply lists, and schedule printouts are weeks when you are already handling family paperwork and already thinking as a team about the months ahead. Adding one folder — the insurance folder — to a table that is already covered in paper costs almost nothing. Reviews that ride on an existing habit tend to happen; reviews that require a special occasion tend to wait for a year that never quite arrives.
The Schedule Change Is an Insurance Issue
It is worth slowing down on this point, because it is the heart of the article. When a child is sick, when school closes early, when a practice is cancelled — the self-employed partner is usually the one who can move things around. That flexibility is a genuine gift to the family. It is also invisible work with a price: hours not billed, projects delayed, clients rescheduled. An employed partner has sick days and paid leave in the background; a self-employed partner has neither. If the self-employed partner is the one who gets sick, or is injured, the household feels it twice — once in lost income and once in lost flexibility.
This is why our pillar guide to disability insurance and income protection for families matters so much for self-employed households. Income protection — insurance that replaces part of an income when illness or injury stops someone working — is the policy that stands behind the flexible partner. Back-to-school season simply makes the need visible: sit down, look at the new weekly schedule honestly, and count how much of the family’s plan depends on one person’s ability to keep working and keep juggling.
What to Review, One Policy at a Time
Health coverage
Start with the coverage the whole family uses. If the employed partner’s job provides the family’s health plan, late summer is the moment to note when that employer’s annual enrollment period falls, and whether anything about your family’s care is changing — a child starting regular therapy, a planned procedure, a prescription that has become permanent. If the self-employed partner buys the family’s coverage individually, check the renewal date and make sure the premium is in the budget alongside the season’s other costs. Terms vary by employer, plan, and state, so treat your own plan documents as the authority.
Income protection
Ask two questions. First: if the self-employed partner could not work for a stretch, what exactly would pay the bills? Second: if the employed partner could not work, what would their job provide, and for how long? Many couples discover the first answer is “our savings, hopefully” and the second is “something through work, we think.” Both answers deserve to become specific. If the self-employed partner looked at disability coverage once and set the idea aside, the start of the school year — when their schedule value is easiest to see — is a kind time to look again. Our plain-English explainer on what insurance for self-employed partners covers walks through the pieces if you are starting from zero.
Life insurance and beneficiaries
Finally, confirm the life insurance picture still matches the family. Coverage amounts do not need re-deciding every year, but beneficiary names — the people you have told each insurer to pay — should be checked whenever family life changes, and the school years change family life constantly. While you are in the paperwork, confirm the names on any policy and on retirement accounts still say what you would want them to say today.
The Paperwork Hour: What to Pull Out
The whole review fits in about an hour if the papers are in front of you. Gather these before you sit down:
| Paperwork | What you are checking |
|---|---|
| Health plan summary (job-based or individual) | Renewal or enrollment dates; whether family care needs have changed |
| Disability policies, individual or through a job | Whose income is covered, and whether the self-employed partner is covered at all |
| Life insurance policies | Amounts still sensible; beneficiary names current |
| A one-page family schedule for the school year | How many hours the self-employed partner’s work depends on, and who absorbs surprises |
| Last year’s notes, if you made any | What you decided last time, so you are reviewing rather than starting over |
If some of these documents do not exist — there is no disability policy, or the life insurance paperwork is a mystery from years ago — that is not a failure of the review. That is the review working. Write the gap on the page, and it becomes the couple’s next project rather than an unpleasant surprise later.
Renewals and Enrollment Windows Ahead
Fall has a rhythm of its own in the benefits world. Many employers run their annual open enrollment — the window when employees can change health plans and related elections for the coming year — sometime in the autumn, and individually bought policies have their own renewal cycles. The exact dates vary by employer, insurer, and state, and no article can hand you yours. What the back-to-school review gives you is timing: you surface the dates in late summer, while there is still room to compare, ask questions, and decide together, instead of in the final rushed days of a window. Couples who have lived through a job change will recognize the same principle — as our companion piece on insurance for self-employed partners after a job change explains, nearly every insurance problem gets easier when the deadlines are known early.
One tax note belongs here, handled carefully. Self-employed people often ask how premiums and business expenses are treated at tax time. Those rules sit with the IRS and they change; the current answer lives on IRS.gov, or with a licensed tax professional. Check there rather than relying on anything in a general article.
A Worked Example: One Couple’s Late-Summer Hour
Priya and Tom are a fictional couple invented for this example, and every figure in it is an invented round number used only to show the method — not a typical cost and not a recommendation. Priya teaches third grade, so the school year shapes her calendar completely. Tom is a self-employed electrician whose two children, in this example, are starting at a new school with an earlier start time.
On a Sunday in late August, they spread the paperwork on the table. The new school schedule means Tom now does the morning drop-off and is the default pickup parent, which trims his billable hours — in their invented example, they estimate his workable week shrinks by about five hours, and they simply write that fact at the top of the page. Priya’s school district health plan covers the family; its enrollment window, in this example, falls in October, so they note the date. Then comes the honest moment: Tom has no disability coverage at all. If his hands were injured, the family’s plan B is Priya’s income and their savings. They do not solve that in the hour — they write “get disability quotes for Tom” as the single action item, and Tom books the calls that week. They confirm beneficiaries on Priya’s life policy through work and on a small individual policy Tom bought years ago, file everything back in one folder, and write three lines of notes so next August starts from this page. Total time: about an hour, most of it conversation they had been meaning to have for two years.
Frequently Asked Questions
Why review insurance in back-to-school season instead of waiting for open enrollment?
Because open enrollment windows are for deciding, and deciding goes better with the thinking already done. A late-summer review surfaces your family’s real care needs, your renewal dates, and any gaps while there is still time to gather information. When the enrollment window opens, you are confirming a plan you made together — not making the whole decision under a deadline.
Our children are not school-age yet. Does this still apply?
Yes — the season is an anchor, not a rule. Any predictable yearly moment works: a work anniversary, a policy renewal month, the start of a school year for a partner who teaches. What matters is that the review is tied to something that recurs on its own. Couples with children in childcare will find the late-summer rhythm still fits, because childcare schedules and costs often shift in the fall too.
What if the self-employed partner has no disability coverage at all?
Then the review has found its most important result. A gap is not an emergency; it is an action item. Learn what individual disability coverage involves, get quotes, and compare them against the reality of your household budget. The starting point is understanding what the policy would need to do — stand behind the income and the schedule flexibility your family relies on every school week.
Does back-to-school season change what health coverage we can buy?
The season itself changes nothing; enrollment rules do. Job-based plans can generally be changed during the employer’s annual enrollment period or after certain life events, and individually bought coverage has its own enrollment windows and life-event exceptions. The details vary, so check your plan documents and, for general background on coverage options, USA.gov. The practical point stands: knowing your dates in August beats discovering them in November.
How do we fit premiums into a month already full of school costs?
By treating the review and the budget as one conversation. Back-to-school spending is lumpy — it arrives in a few weeks — while premiums are steady. When couples lay the two side by side in August, they can smooth the lumpy part (start supplies earlier next year, spread fees where the school allows) instead of letting a crowded month squeeze out the steady payments that keep coverage in force. If money is genuinely tight, that is information for the review, not a reason to skip it.
What should we write down so next year’s review is faster?
Three things: the dates (renewals, enrollment windows, premium due dates), the decisions (what you kept, changed, or chose not to change, and why), and the gaps (anything missing, with the next step you agreed on). One page is enough. Next year you will spend the hour updating a page instead of reconstructing a year.
Your Next Step
Before the school year settles in, pick one evening and pull out the five pieces of paperwork in the table above — or as many of them as exist. For each policy, write down its renewal or enrollment date and one line: still fits, needs a change, or missing entirely. That single page is the whole foundation. Everything else — quotes, comparisons, decisions — can follow at a calmer pace, but it all starts with seeing your family’s protection on one page while the new school-year schedule is right in front of you.
Related Articles
- Disability Insurance and Income Protection: Guarding the Paycheck Your Plans Rest On
- What Is Insurance for Self-Employed Partners? A Plain-English Guide for Couples
- Insurance for Self-Employed Partners After a Job Change: What Changes First
This article is for general educational purposes only and is not financial, tax, legal, or investment advice. Consult a licensed professional about your situation.